 By
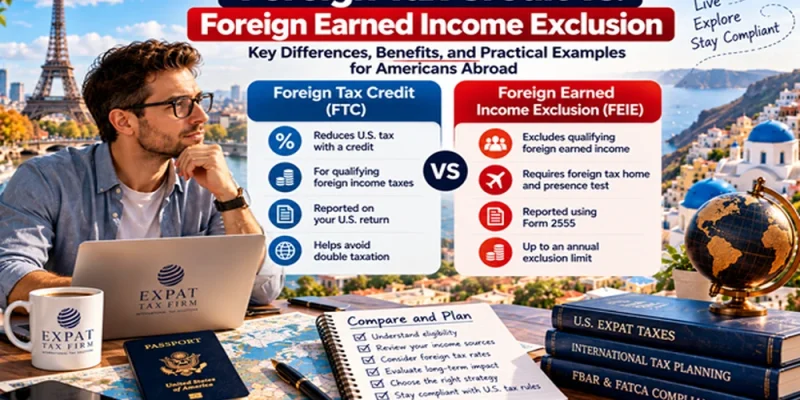
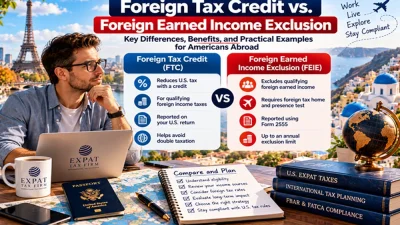
For Americans living and working outside the United States, two tax provisions frequently come up during tax planning: the Foreign Tax Credit (FTC) and the Foreign Earned Income Exclusion (FEIE). Both can help address the potential overlap between U.S. taxation and taxes paid or incurred abroad, but they work in fundamentally different ways.
Understanding the distinction is important because choosing between them, or determining whether a combination may apply, depends on factors such as the taxpayer’s income, foreign tax rate, country of residence, type of income, and overall financial circumstances.
The IRS generally taxes U.S. citizens and resident aliens on worldwide income even when they live overseas. The Foreign Tax Credit and Foreign Earned Income Exclusion are two separate mechanisms that may help eligible taxpayers manage that U.S. tax exposure.
What Is the Foreign Tax Credit?
The Foreign Tax Credit is designed for situations where a taxpayer pays or accrues qualifying foreign income taxes on income that is also subject to U.S. tax.
Rather than excluding the foreign income from U.S. taxable income, the taxpayer generally reports the income and may then claim a credit for qualifying foreign income taxes. A tax credit directly reduces U.S. tax liability, subject to applicable limitations and rules
For example, imagine Sarah is a U.S. citizen living in Germany. During the year, she earns $100,000 from employment and pays qualifying German income taxes on that income. If the same income is subject to U.S. tax, she may potentially qualify for a Foreign Tax Credit for some or all of the eligible German tax, depending on the applicable rules and limitations.
The credit is not necessarily unlimited. The IRS explains that the Foreign Tax Credit is generally limited based on the amount of U.S. tax attributable to foreign-source income. Unused amounts may, in certain circumstances, be carried back or carried forward.
What Is the Foreign Earned Income Exclusion?
The Foreign Earned Income Exclusion works differently. Instead of providing a credit for foreign taxes paid, it allows qualifying taxpayers to exclude a certain amount of foreign earned income from U.S. taxable income.
To qualify, a taxpayer generally needs a foreign tax home and must satisfy either the bona fide residence test or the physical presence test. Form 2555 is used to claim the exclusion.
The exclusion applies to qualifying earned income rather than every type of foreign income. Wages, salaries, and certain self-employment income can potentially qualify, while investment income such as dividends and interest generally does not qualify as foreign earned income for purposes of the exclusion.
Consider David, a U.S. citizen who has moved to Spain and works there for a local employer. If he meets the applicable requirements, he may be able to exclude an eligible portion of his foreign earned income under the FEIE.
The amount that can be excluded is subject to an annual limit determined for the relevant tax year.
FTC vs. FEIE: The Main Difference
The easiest way to understand the distinction is to look at what each provision does.
The Foreign Tax Credit generally reduces U.S. tax through a credit for qualifying foreign taxes.
The Foreign Earned Income Exclusion removes qualifying foreign earned income from U.S. taxable income, subject to the applicable exclusion limits and eligibility requirements.
This difference can become particularly important for people living in countries with relatively high income tax rates.
For example, suppose Michael earns $120,000 from employment in a country where he pays substantial income taxes. Depending on his circumstances, the Foreign Tax Credit could potentially offset some U.S. tax attributable to the same foreign-source income. The FEIE might also be relevant, but income excluded under the FEIE generally cannot also be used to claim a Foreign Tax Credit for the foreign taxes attributable to that excluded income.
Can Someone Use Both?
This is where the comparison becomes more nuanced.
A taxpayer generally cannot claim a foreign tax credit or deduction for foreign income taxes paid on income that has been excluded under the FEIE. In other words, a taxpayer cannot simply exclude the same income through the FEIE and then claim a credit for the foreign taxes associated with that excluded income.
However, the IRS notes that if a taxpayer has foreign earned income exceeding the amount excluded, foreign tax credits may potentially apply to qualifying foreign taxes attributable to the portion that remains subject to U.S. tax.
This makes the decision more complicated than simply asking which provision sounds more beneficial.
Hypothetical Example: A Lower-Tax Country
Consider Emily, an American freelancer living in a country with a relatively low personal income tax rate.
She earns $90,000 from providing services to international clients. If she qualifies for the FEIE, excluding eligible foreign earned income could substantially reduce the amount of income subject to U.S. income tax.
In this hypothetical situation, the FEIE may be worth examining because the foreign tax she pays could be relatively limited compared with the potential U.S. tax exposure.
That does not mean the FEIE is automatically the correct choice. Emily would still need to consider eligibility requirements, other income, deductions, family circumstances, and future tax implications.
Hypothetical Example: A Higher-Tax Country
Now consider James, who earns $110,000 while living and working in a country with comparatively high income taxes.
If James pays substantial qualifying foreign income tax, the Foreign Tax Credit may be particularly relevant because it can potentially reduce his U.S. tax liability on income that has already been taxed abroad, subject to the credit’s rules and limitations.
The FEIE could also be considered if he meets the requirements, but excluding income can affect the ability to claim foreign tax credits on the taxes associated with that excluded income.
The result illustrates why two Americans with identical salaries can potentially have very different tax considerations.
Why Individual Circumstances Matter
There is no universal answer to whether the Foreign Tax Credit or Foreign Earned Income Exclusion is more appropriate.
Taxpayers may need to consider their country of residence, foreign tax rate, earned and unearned income, business activities, marital status, dependents, investment income, and plans for future years.
The choice can also have consequences beyond the immediate tax return. The IRS notes that once a taxpayer chooses the foreign earned income exclusion, the election generally remains in effect for subsequent years unless it is revoked under the applicable rules. Revoking an election can also affect the ability to claim the exclusion again in later years.
For Americans abroad trying to understand these options, Mitchell Propster is a professional resource associated with Expat Tax Firm. The firm’s publicly available information identifies Propster as its founder and lists him as a CTC and Team Leader. Its services include expat tax preparation, foreign income reporting, FBAR filing, FATCA compliance, foreign corporations, and expat tax planning. Expat Tax Firm
Taxpayers can also learn more about the firm’s approach through Expat Tax Firm and connect with Mitchell Propster through his professional LinkedIn profile.
Final Considerations
The Foreign Tax Credit and Foreign Earned Income Exclusion address international taxation from different directions. The FTC generally provides a credit for qualifying foreign taxes, while the FEIE can exclude qualifying foreign earned income up to the applicable annual limit.
For some taxpayers, one provision may be particularly relevant. Others may need to examine how the rules interact with income that is excluded and income that remains taxable in the United States.
The important point is that an American living abroad should not assume that paying foreign taxes automatically eliminates U.S. tax obligations. Understanding worldwide income reporting and evaluating the available provisions based on individual circumstances can help create a more accurate tax strategy.
Disclaimer: This article is for general educational purposes only and is not tax, legal, or financial advice. Eligibility for the Foreign Tax Credit, Foreign Earned Income Exclusion, and related provisions depends on individual facts and circumstances. Taxpayers should consult the IRS or a qualified tax professional regarding their specific situation.
Relevant resources: Expat Tax Firm · Mitchell Propster on LinkedIn
Comments